Ever wonder how much auto insurance in Massachusetts actually costs? You’re not alone. Navigating the myriad of insurance options and understanding what influences rates in the Bay State can be a daunting task for many drivers.
In this guide, we’ll break down everything you need to know about auto insurance in Massachusetts with a flair that only Backlinko can provide. From essential coverage requirements to smart strategies for saving on your premium, we’ve got you covered.
Overview of Auto Insurance in Massachusetts
Did you know that in Massachusetts, drivers are required to have at least four types of auto insurance coverage? That’s right! You’re not just grabbing any policy off the shelf.
Let me break it down for you. The Bay State mandates a minimum level of coverage for Bodily Injury to Others, Personal Injury Protection (PIP), Bodily Injury Caused by an Uninsured Auto, and Damage to Someone Else’s Property. These aren’t just suggestions. They’re the law.
Types of Auto Insurance Coverage in Massachusetts
Here’s the deal: not all coverage is created equal. You have options like liability coverage, which is mandatory, but there’s also comprehensive and collision coverage if you want extra protection. And let’s not forget uninsured motorist coverage. It’s an extra layer of security if you ever get hit by someone without insurance.
Pro Tip: Always check if your policy offers accident forgiveness. It could save you big time if you’re ever at fault in an accident.
Factors Influencing Auto Insurance Rates
Why do rates differ so much between drivers? Well, it boils down to a few key factors. Your driving record plays a massive role. But there are other players in the game too:
- Your age and gender can affect your rates.
- Your vehicle type and driving location are considered.
- Even your credit score might influence what you pay.
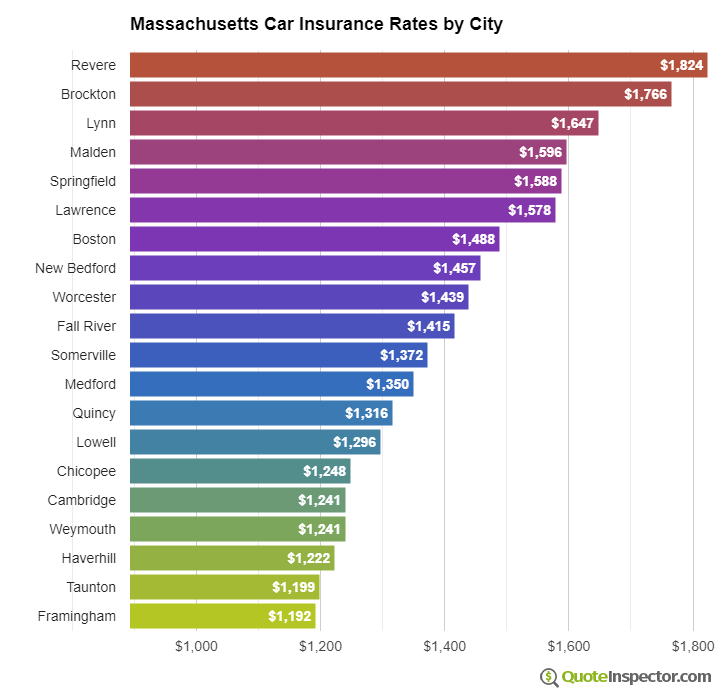
Here’s the kicker: living in a busy city like Boston might hike up your rates compared to the quieter landscapes of the Berkshires.
Cost Factors for Auto Insurance

Ever wondered why your auto insurance rate is what it is? It’s not just a roll of the dice. The cost of your auto insurance in Massachusetts is influenced by several key factors. Let’s dive into what makes that premium tick.
Your premium isn’t just about luck. It’s a calculated number based on various factors like where you live, your driving record, and the car you drive. Understanding these can help you make smarter decisions and potentially save money.
Location Matters: The Massachusetts Effect
Where you live in Massachusetts can have a huge impact on your auto insurance rates. Urban areas like Boston tend to have higher rates due to increased traffic and accident probabilities. Conversely, rural areas often see lower premiums because of fewer cars on the road.
Vehicle Type: Not All Cars Are Created Equal
The type of vehicle you drive also plays a critical role. High-performance cars or luxury vehicles are more expensive to insure due to higher repair costs and increased theft risk. On the flip side, a standard sedan might cost you less.
| Vehicle Type | Average Premium |
|---|---|
| Luxury Car | $1,500/year |
| Standard Sedan | $1,000/year |
Driving Record: Your Personal History
Your driving record is a biggie. A clean record could mean a significantly lower premium, while accidents or traffic violations can skyrocket your rates. Insurance companies see your past behavior as a predictor of future risk.
Pro Tip: Keep a clean driving record to maximize your savings.
Average Auto Insurance Costs in Massachusetts
Did you know that auto insurance in Massachusetts can cost anywhere between $1,200 and $2,000 annually? That’s a hefty sum. But let’s break it down further because one size doesn’t fit all.
Auto insurance costs vary widely depending on several factors, including coverage levels, demographics, and vehicle types. You might think you’re getting a good deal, but there’s a lot more under the hood.
Insurance Costs Based on Coverage Levels
When it comes to coverage, your choice can significantly impact your wallet. Here’s a quick look at the average costs for different levels of coverage:
| Coverage Level | Average Annual Cost |
|---|---|
| Minimum Coverage | $1,200 |
| Standard Coverage | $1,500 |
| Full Coverage | $2,000 |
As you can see, opting for full coverage could cost you an extra $800 annually compared to minimum coverage. So, choose wisely!
Cost Variations for Different Demographics and Vehicle Types
Not all drivers are treated equally when it comes to insurance costs. Age, gender, and the type of car you drive all play a part. Consider this: a young male driver with a sports car will likely pay much more than an older female driver with a sedan.
- Young Drivers: Expect to pay around $2,500 annually.
- Older Drivers: Can pay as low as $1,100 annually.
- Sports Cars: Insurance could spike up to $3,000 annually.
- Sedans: Typically around $1,200 annually.
Pro Tip: Always compare quotes from multiple insurance providers to snag the best deal!
The game changes based on who you are and what you drive. Don’t fall into the trap of thinking that everyone pays the same. Keep these factors in mind, and you’ll be better equipped to handle your auto insurance negotiations.
Saving on Auto Insurance
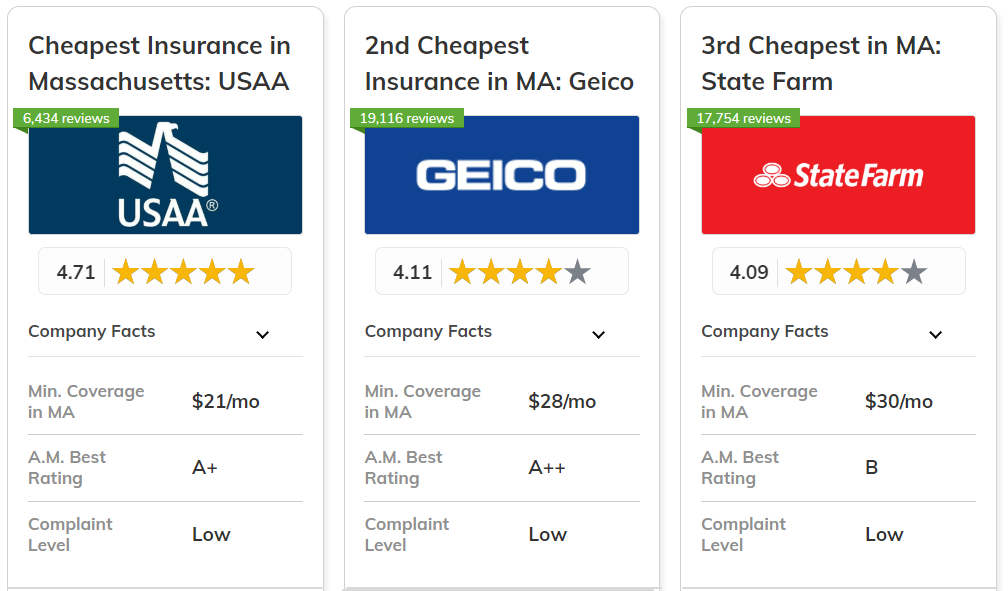
Did you know that the average American could save up to $859 annually just by tweaking their auto insurance plan? That’s right! By taking a few strategic steps, you can significantly reduce your premiums.
Let’s dive into some practical ways to cut down your auto insurance costs while still getting the coverage you need.
Strategies to Reduce Auto Insurance Premiums
One of the quickest ways to cut your premium is by bundling your policies. By combining your auto insurance with home or renter’s insurance, many companies offer discounts. Consider raising your deductible too. It means paying more out-of-pocket in case of an accident, BUT it can slash your monthly bill.
Pro Tip: Adjust your coverage limits if your car is older. You might not need extensive collision or comprehensive coverage, saving you a bundle.
Effective Methods for Comparing Auto Insurance Quotes
Comparing auto insurance quotes isn’t just about price. It’s about finding the best value. Use online comparison tools to get a broad view of the market. But don’t just settle for online quotes! Call insurance agents directly to negotiate better rates. They often have flexibility you won’t see online.
Here’s the deal: Always check the coverage details and exclusions. A cheaper policy might exclude crucial coverage that could cost you more in the long run.
Discounts and Incentives in Massachusetts
Massachusetts insurers offer a variety of discounts that you might qualify for. Good student? You could get a lower rate. Have a clean driving record? More savings for you! Many companies also give breaks for low mileage drivers or if you use telematics devices to monitor safe driving habits.
Step #1: Ask your provider about these incentives. Step #2: Provide any necessary documentation to prove eligibility. These discounts can add up to serious savings over time.
Legal Aspects and Regulations
Did you know that 96% of drivers in Massachusetts hold auto insurance? It’s not just smart; it’s the law. If you drive in the Bay State, you better have your insurance game on point.
Massachusetts has some of the strictest auto insurance regulations in the U.S. Why? To protect drivers and ensure that everyone can cover the costs if accidents happen. But if you’re caught without it, you’ll face significant fines, license suspension, and more.
Understanding Massachusetts Auto Insurance Requirements
Here is the deal: You can’t just drive with any insurance. The state demands certain minimum coverage levels. You need at least:
- $20,000 per person for bodily injury.
- $40,000 total per accident for bodily injury.
- $5,000 for property damage.
- Uninsured motorist coverage mirroring the bodily injury limits.
These are the bare minimums. Opting for more coverage could save you big bucks in the long run. You never know when a higher limit will save your financial bacon.
Penalties for Skipping Insurance
Getting caught without insurance isn’t a small deal. Imagine losing your license or facing fines up to $5,000. Ouch! Plus, you’ll have to pay a reinstatement fee to get back on the road. Your insurance premiums could skyrocket after this costly mistake.
These penalties are designed to make you think twice about skipping coverage. It’s not just about obeying the law; it’s about protecting yourself and others.
Steps to Take If Involved in an Accident Without Adequate Insurance
Picture this: You’re in a fender bender, and your insurance is lacking. What now? First, stay calm and follow these crucial steps:
- Exchange information with the other driver, including insurance details.
- Contact the police to file a report. This is vital for documentation.
- Notify your insurance company (even if coverage is inadequate).
- Seek legal advice to understand your liabilities and options.
- Prepare for potential civil suits or claims from the other party.
Pro Tip: Never admit fault at the scene. Let the professionals handle that.
Running through these steps will help you limit damage, both financial and legal, when the unexpected strikes.
Trends and Future Considerations
Auto insurance in Massachusetts is in a state of flux. With technological advancements and evolving consumer needs, the way insurance is priced and delivered is changing rapidly.
Everyone’s talking about autonomous vehicles and their impact on the industry. But there’s more to the story. From telematics to climate change, multiple factors are reshaping the auto insurance landscape. Here’s how these trends are affecting you.
Technological Advancements and Their Impact
Have you heard of telematics? This is a game-changer in the auto insurance world. By installing a small device in your car, insurers can track your driving habits in real-time. This means if you’re a safe driver, you could end up paying a lot less on your premiums.
Pro Tip: If you drive safely, consider opting into a telematics program to potentially lower your rates.
But, there’s a flip side. If your driving style is less than stellar, you might see higher premiums. So, it’s crucial to weigh the pros and cons before jumping in.
Future Landscape of Auto Insurance in Massachusetts
The rise of electric vehicles (EVs) is another trend to watch. As more people switch to EVs, insurance companies are adjusting their models to account for new risks and benefits associated with these vehicles. While EVs can be more expensive to repair, they also tend to be involved in fewer accidents.
And let’s not forget about climate change. With increasing instances of extreme weather, insurers are recalibrating their risk assessments. This might lead to fluctuating rates based on where you live and drive in Massachusetts.
Here’s the deal: The future of auto insurance in Massachusetts is dynamic. Staying informed and adaptable will help you navigate these changes effectively.
Final Thoughts
Understanding how much auto insurance is in Massachusetts doesn’t have to be a puzzle. Armed with the right insights and strategies, you can make informed decisions that keep you protected without breaking the bank. So, buckle up and take control of your auto insurance journey!
Frequently Asked Questions
What are the minimum auto insurance requirements in Massachusetts?
Massachusetts law requires a minimum of $20,000 per person and $40,000 per accident for bodily injury liability, $5,000 for property damage, and personal injury protection (PIP) of $8,000.
How does my location affect auto insurance rates in Massachusetts?
Your location can significantly impact your insurance rates due to factors like crime rates, traffic density, and local accident statistics. Urban areas tend to have higher premiums.
What can I do to lower my auto insurance premiums?
Drivers can reduce premiums by bundling policies, maintaining a clean driving record, opting for a higher deductible, and taking advantage of available discounts.
Are there discounts available for auto insurance in Massachusetts?
Yes, many insurers offer discounts for safe driving, multiple policies, anti-theft devices, and more. It’s beneficial to ask your provider about specific discounts.
Is having a good credit score important for auto insurance rates?
While Massachusetts does not allow the use of credit scores to determine auto insurance rates, maintaining a good score is still vital for overall financial health.
How does my vehicle type influence my insurance costs?
Generally, high-performance and luxury vehicles have higher premiums due to increased repair costs and theft risk. Opting for a safer, more reliable car can lower costs.
What happens if I drive without insurance in Massachusetts?
Driving without insurance can result in fines, license suspension, and higher future premiums. Always ensure you meet the state’s insurance requirements.
